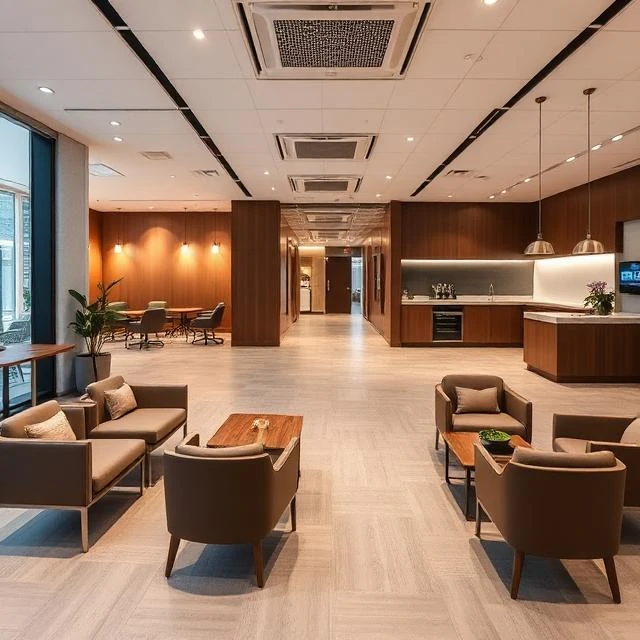
A branch is a physical location where a bank offers services to customers. It is where you open an account, apply for a loan, deposit a check, or talk to a banker face to face. Branches have been the public face of banking for centuries. Their numbers are shrinking, but they are not disappearing.
The branch model has changed. In the past, branches were transaction factories, with tellers handling deposits, withdrawals, and payments. Now most of those transactions happen online or at ATMs. Branches are becoming advice centers, where customers meet with bankers to discuss mortgages, investments, and small business loans. The layout has changed too. Fewer teller windows, more private offices and meeting spaces.
Branch closures have been controversial. When a bank closes a branch in a rural or low-income neighborhood, customers lose easy access to financial services. Elderly customers and small businesses are hit hardest. Some communities become banking deserts, with no branch within miles. Regulators and community groups have pushed back, and some banks have responded with mobile branches and shared facilities.
The largest banks have thousands of branches. JPMorgan Chase has over 4,700. Bank of America has about 3,800. Wells Fargo has about 4,200. The numbers are declining by a few percent each year. But the branch remains important for complex transactions and for customers who prefer human contact.
Comments
No comments yet. Be the first to share a thought.
Leave a comment