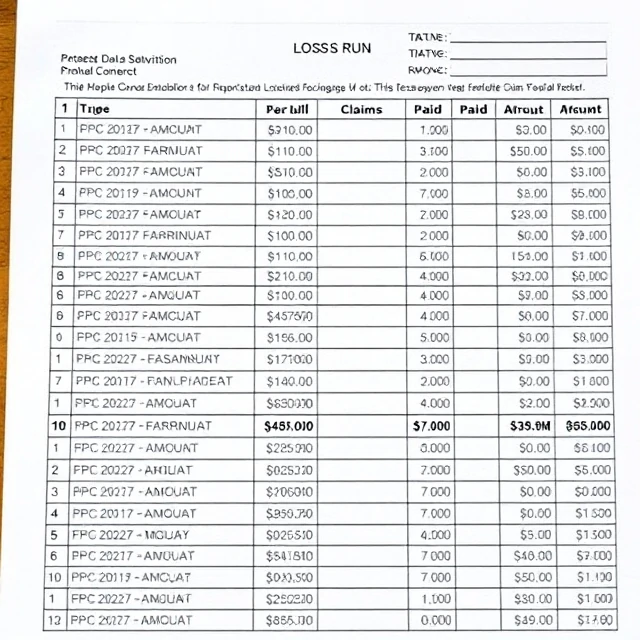
Underwriters and risk managers need a clear view of past claims. A loss run is a report, usually produced by the insurer or third-party administrator, that lists an insured’s claims over a specified period, showing dates, types of loss, amounts paid, and reserves.
Loss runs support experience rating, renewal underwriting, and risk-management analysis. They reveal frequency patterns, large-loss severity, and the types of incidents driving cost. Valuable loss runs include claim status, recovery amounts, and enough narrative to understand causation.
Requesting loss runs well before renewal allows time for analysis and for correcting any errors. Incomplete or delayed loss runs hinder competitive bidding and accurate pricing. Many insurers now provide online access so that insureds and brokers can retrieve current loss runs as needed.
- Report of an insured’s historical claims
- Shows dates, amounts, and claim status
- Used for underwriting and risk management
- Should be obtained and reviewed before renewal
Comments
No comments yet. Be the first to share a thought.
Leave a comment