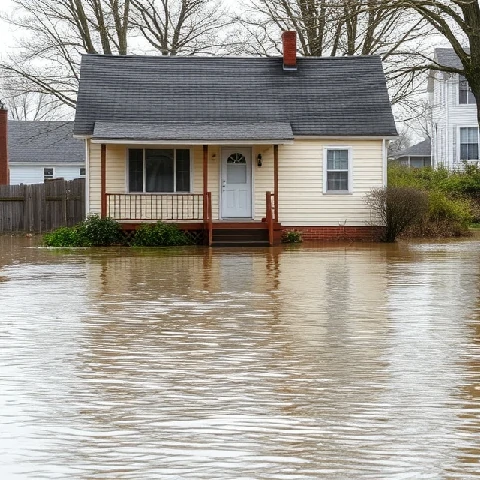
Rising water is excluded from almost every standard homeowners policy. Flood insurance covers direct physical loss to buildings and contents caused by flooding, defined generally as inundation of normally dry land by overflowing inland or tidal waters or by unusual rapid accumulation of runoff.
In the United States most flood insurance is written through the National Flood Insurance Program, with private insurers participating as write-your-own carriers. Coverage limits, deductibles, and waiting periods are standardized. Elevation certificates and flood-zone determinations affect both eligibility and cost.
Private flood insurance has expanded in recent years as alternative capacity enters the market. Whether public or private, the coverage is essential for properties in flood-prone areas. Claims require documentation of the water source and the extent of damage; continuous coverage is often needed to obtain full replacement-cost benefits.
- Coverage for damage caused by flooding
- Excluded from standard homeowners policies
- Often provided through government-backed programs
- Subject to flood-zone rating and waiting periods
Comments (2)
Leave a comment